
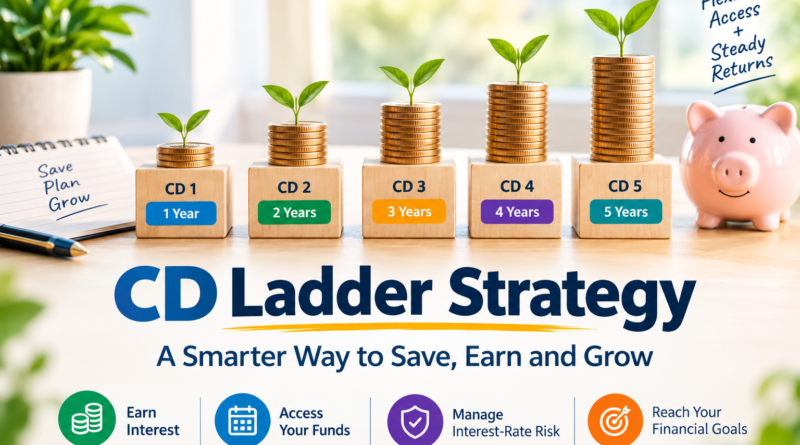
CD Ladder Strategy: A Complete Guide to Smarter Savings
Introduction to CD Ladder Strategy
A CD ladder strategy is a savings approach that allows people to earn interest on their money while keeping regular access to portions of their savings. It involves dividing your money among several Certificates of Deposit (CDs) with different maturity dates instead of placing all your savings into a single CD.
Certificates of Deposit are financial products offered by banks and credit unions. When you open a CD, you deposit a specific amount of money for a fixed period. In return, the financial institution generally pays interest at an agreed rate. Depending on the CD terms, withdrawing money before maturity may result in an early withdrawal penalty.
The main challenge with traditional CDs is that your money may remain locked away for months or years. If interest rates rise after you open a long-term CD, you might miss the opportunity to earn a higher rate elsewhere. On the other hand, keeping all your money in short-term CDs may mean earning less interest than you could receive from longer-term deposits.
A CD ladder helps address these challenges by spreading your savings across CDs with different maturity dates. As each CD matures, you can withdraw the money if you need it or reinvest it in another CD to continue your savings plan.
This strategy can be useful for people who want predictable interest earnings, relatively low-risk savings, and a structured approach to managing cash. However, the right approach depends on your financial goals, access to emergency funds, interest rates, and the terms offered by your bank.
In this guide, you will learn how a CD ladder works, how to build one, its advantages and disadvantages, common mistakes to avoid, and how to decide whether this savings strategy fits your needs.
What Is a CD Ladder Strategy?
A CD ladder strategy involves dividing your savings into several Certificates of Deposit with different maturity periods. Each CD matures at a different time, creating opportunities to access some of your money periodically without closing every account early.
For example, suppose you have $5,000 available for savings. Instead of placing the entire amount into one five-year CD, you could divide it into five deposits of $1,000 each.
You might open the following CDs:
| CD | Deposit | Term |
|---|---|---|
| CD 1 | $1,000 | 1 year |
| CD 2 | $1,000 | 2 years |
| CD 3 | $1,000 | 3 years |
| CD 4 | $1,000 | 4 years |
| CD 5 | $1,000 | 5 years |
These CDs have different maturity dates, so your money does not become available all at once. After the first year, your one-year CD matures. You can withdraw the funds or reinvest them in a new CD, depending on your financial needs and the interest rates available.
As the remaining CDs mature, you can continue the same process.
The purpose is to balance access to savings with the potential benefits of locking in interest rates for longer periods. It also reduces the need to predict exactly when interest rates will rise or fall.
A CD ladder does not guarantee the highest possible return. Instead, it provides a structured way to spread maturity dates and manage savings over time.
How Does a CD Ladder Work?
A CD ladder works by assigning different portions of your savings to CDs with different terms. Each deposit earns interest according to its account agreement, and the money generally becomes available when that CD reaches maturity.
The process is relatively simple.
1. Divide Your Savings
Start by deciding how much money you can comfortably commit to CDs. Avoid including money that you may need immediately for rent, groceries, medical expenses, or unexpected bills.
For example, if you have $10,000 in savings and $3,000 is needed for emergencies, you might consider allocating only the remaining $7,000 to a CD ladder, provided that other near-term financial needs are covered.
2. Select Different CD Terms
Choose maturity periods that fit your financial goals. A common approach is to use one-year, two-year, three-year, four-year, and five-year CDs.
However, you do not have to use five CDs. A smaller ladder with three different maturity periods may be more practical if you have limited savings or want a simpler structure.
3. Compare Interest Rates
Before opening each CD, compare the annual percentage yield (APY), minimum deposit, compounding rules, early withdrawal penalties, and maturity options.
A longer-term CD may offer a higher APY, but that is not always the case. Sometimes short-term CDs offer competitive rates, particularly when banks expect interest rates to decline.
4. Allow Each CD to Mature
When a CD reaches its maturity date, the bank generally provides a specified maturity or grace period during which you can withdraw the funds, change the CD term, or select another available option.
The length of this period depends on the financial institution.
5. Reinvest or Withdraw the Funds
If you do not need the money, you can reinvest the matured CD into a new longer-term CD. If you need cash, you can withdraw the proceeds instead.
Over time, this process creates a repeating cycle in which portions of your savings become available at regular intervals.
Types of CD Ladder Strategies
There are several ways to structure a CD ladder. The best option depends on how much money you have, when you expect to need it, and how comfortable you are with locking in savings.
Traditional CD Ladder
A traditional CD ladder spreads deposits across several terms, such as one through five years.
Once the first CD matures, you can reinvest it in a new five-year CD. The same process continues as each shorter-term CD reaches maturity.
This approach gradually establishes a ladder in which one CD matures approximately every year.
It can suit savers who have a relatively long time horizon and want a combination of regular access and longer-term interest-rate exposure.
Short-Term CD Ladder
A short-term CD ladder uses CDs with shorter maturities, such as three, six, nine, and twelve months.
This structure can be appropriate for people who may need their money within the next year or who prefer not to commit to long-term deposits.
Shorter terms provide more frequent opportunities to review interest rates and financial needs. However, they may offer lower yields than some longer-term CDs, depending on market conditions.
Long-Term CD Ladder
A long-term CD ladder focuses on longer maturities, such as two, three, four, and five years.
It may be suitable for savings that you do not expect to use soon. If rates are attractive when you open the CDs, you can lock in those rates for the agreed terms.
The main disadvantage is that your money may be less accessible for extended periods. Early withdrawals can result in penalties, and rising market rates may make existing CDs less competitive.
Mini CD Ladder
A mini CD ladder uses two or three CDs rather than a large collection of accounts.
For example, you could divide $3,000 into three deposits of $1,000 each, using three-, six-, and twelve-month terms.
This option is easier to manage and may be useful for beginners who want to test the strategy before committing more money.
CD Ladder Strategy Example
Consider a saver who has $10,000 available for a CD ladder and wants to spread the money across five maturity periods.
For illustration, assume the saver opens five CDs with $2,000 each and receives different APYs.
| CD term | Initial deposit | Illustrative APY |
|---|---|---|
| 1 year | $2,000 | 3.50% |
| 2 years | $2,000 | 3.70% |
| 3 years | $2,000 | 3.80% |
| 4 years | $2,000 | 3.90% |
| 5 years | $2,000 | 4.00% |
| Total | $10,000 | — |
These rates are hypothetical examples, not current market offers. Actual APYs vary by institution and can change over time.
Suppose the one-year CD earns 3.50% APY. If the interest is compounded according to that APY and remains in the account for a full year, the balance would grow to approximately $2,070.
At maturity, the saver could withdraw the $2,070 or reinvest it in a new CD.
If the saver reinvests the matured funds, the new rate will depend on the offers available at that time. It may be higher or lower than the original rate.
The other CDs continue earning interest according to their respective agreements.
This example illustrates how a CD ladder can distribute maturity dates across several years. It does not mean the saver will earn the same rate on every future reinvestment.
Benefits of a CD Ladder Strategy
A CD ladder offers several advantages for people who want a disciplined savings plan without investing all their money in a single fixed-term deposit.
1. Regular Access to Savings
One of the most important benefits is that portions of your money become available at different times.
If you put all your savings into a five-year CD, you may need to pay a penalty to access the money early. With a ladder, you can plan around scheduled maturity dates.
However, not every CD matures frequently. The access you receive depends on the terms you select.
2. Predictable Interest Earnings
Traditional fixed-rate CDs generally offer a stated interest rate for the agreed term.
This can make it easier to estimate how much interest a deposit may earn before maturity. It also helps you plan for specific savings goals.
The exact amount depends on the APY, deposit, compounding arrangements, and any applicable account terms.
3. Reduced Interest-Rate Timing Risk
Predicting future interest rates is difficult. A CD ladder spreads your deposits across different terms, so you do not have to commit all your savings at one moment.
If rates rise, maturing CDs give you opportunities to reinvest at potentially higher rates. If rates fall, longer-term CDs that you already opened may continue earning their original fixed rates until maturity.
The ladder does not eliminate interest-rate risk, but it distributes the timing of reinvestment decisions.
4. Encourages Consistent Saving
A CD ladder can help you organize savings into separate accounts with specific maturity dates.
This structure may reduce the temptation to spend money intended for longer-term goals. It can also encourage you to review your financial situation regularly.
5. Potential Deposit Protection
Eligible CDs held at an FDIC-insured U.S. bank may qualify for deposit insurance within applicable limits. Eligible deposits at federally insured U.S. credit unions may receive NCUA insurance.
Coverage depends on ownership category, institution, and total eligible deposits. Multiple CDs at the same institution do not automatically receive separate insurance limits merely because they are separate accounts.
A CD ladder is not automatically risk-free, so you should verify the institution’s insurance status and applicable coverage.
Disadvantages of a CD Ladder Strategy
Although CD ladders can be useful, they are not the right choice for every saver.
1. Early Withdrawal Penalties
Many traditional CDs charge a penalty if you withdraw money before maturity.
Depending on the agreement, the penalty may consume some of the interest you earned and could reduce your principal in certain circumstances.
For this reason, avoid placing emergency savings or money needed for near-term expenses into CDs with restrictive withdrawal terms.
2. Reinvestment Risk
When a CD matures, the available rates may be lower than the rate you previously received.
For example, a CD earning 4% APY today might mature when similar CDs offer only 2.5% APY.
If you reinvest at the lower rate, future interest earnings may decrease.
A CD ladder spreads reinvestment dates but cannot prevent rates from falling.
3. Inflation Risk
Inflation reduces the purchasing power of money over time.
Suppose a CD earns 3% APY while inflation averages 4% during the same period. The approximate real return before taxes would be negative 1%.
The precise real return depends on the relationship between the effective investment return and inflation. Taxes can reduce the return further.
CDs can preserve nominal savings, but they do not guarantee that your money will grow faster than living costs.
4. Lower Potential Growth Than Some Investments
Stocks and other investments may offer greater long-term growth potential, although they also involve market risk and can lose value.
A CD ladder prioritizes predictable returns and scheduled access rather than maximizing long-term investment growth.
For long-term goals such as retirement, a CD ladder may be one component of a broader financial plan rather than a complete investment strategy.
5. Account Management
A ladder containing several CDs requires you to track maturity dates, interest rates, renewal instructions, and withdrawal deadlines.
If you forget to review a maturing CD, your bank may automatically renew it according to its renewal rules. That could lock your money into a term you did not intend to choose.
Calendar reminders and a simple savings spreadsheet can help you stay organized.
How to Build a CD Ladder Step by Step
Creating a CD ladder does not require complicated financial knowledge. A clear plan can help you choose suitable terms and avoid unnecessary penalties.
Step 1: Define Your Savings Goal
Start by identifying why you are saving.
Your goal might be a house deposit, a future tuition payment, a planned purchase, or additional savings for retirement.
The time when you need the money should influence the CD terms you choose.
If you need the entire amount in six months, putting most of it into five-year CDs may not be appropriate.
Step 2: Establish an Emergency Fund
Before building your ladder, keep enough accessible cash for emergencies and predictable short-term expenses.
An emergency fund is generally best held in an account that provides convenient access, such as a suitable savings account.
The appropriate amount depends on your income stability, household expenses, debts, and personal circumstances.
Step 3: Decide How Much to Deposit
Determine how much money you can set aside without affecting essential expenses.
You do not need a large balance to begin. Some banks offer CDs with relatively low minimum deposits, while others require larger amounts.
Check the minimum deposit requirements before selecting a financial institution.
Step 4: Choose the Ladder Structure
Select the number of CDs and their maturity periods.
For example, you might use three CDs with six-month, one-year, and eighteen-month terms. Alternatively, you could use a five-year ladder if you have longer-term savings and can comfortably leave the money deposited.
Choose a structure that fits your actual cash-flow needs rather than simply choosing the largest number of CDs.
Step 5: Compare Banks and Credit Unions
Review several financial institutions before opening your accounts.
Pay attention to:
- Annual percentage yield.
- Minimum opening deposit.
- Early withdrawal penalties.
- Interest payment and compounding arrangements.
- Automatic renewal rules.
- Grace period after maturity.
- Deposit insurance eligibility.
- Online account access and customer service.
A slightly higher APY may not be worthwhile if the account has restrictive conditions that do not suit your needs.
Step 6: Open the CDs
After comparing available options, open each CD with the amount and term you selected.
Keep a record of each account’s opening date, maturity date, interest rate, and renewal instructions.
You can store these details in a spreadsheet or a personal financial planner.
Step 7: Review Each Maturity Date
Set reminders before every CD matures.
Review your financial needs and compare available rates before deciding whether to renew, change the term, or withdraw the money.
Do not assume that an automatic renewal will provide the best rate or the most appropriate maturity period.
Step 8: Reinvest According to Your Plan
When a CD matures, decide whether you need the money or can continue saving it.
If you reinvest, compare current rates and select a term consistent with your overall ladder. Reinvesting in a longer-term CD may help maintain the ladder’s structure, but it is not compulsory.
Your strategy should remain flexible enough to accommodate changes in income, expenses, and financial goals.
CD Ladder vs. a Single Long-Term CD
A CD ladder and a single long-term CD can both help savers earn interest, but they serve different purposes.
| Feature | CD ladder | Single long-term CD |
|---|---|---|
| Maturity dates | Spread across several dates | One maturity date |
| Access to funds | Portions mature periodically | Most funds mature together |
| Account management | More involved | Usually simpler |
| Rate exposure | Reinvestment occurs at different times | Rate is generally fixed for the chosen term |
| Early withdrawal penalties | Depend on each CD’s terms | May apply to the entire deposit |
| Best suited for | Staggered access and flexibility | Money not needed until maturity |
A CD ladder may be preferable if you want regular opportunities to access portions of your savings. A single CD may be more convenient if you have a specific date when you expect to need the entire amount.
Neither option is universally better. Compare the available APYs and account conditions before making a decision.
CD Ladder vs. a High-Yield Savings Account
A high-yield savings account is another option for people who want to earn interest on cash.
The main difference is liquidity. Savings accounts generally allow more convenient withdrawals, subject to the institution’s account rules. Traditional CDs usually require you to wait until maturity or pay a penalty for an early withdrawal.
| Feature | CD ladder | High-yield savings account |
|---|---|---|
| Interest rate | Often fixed for each CD’s term | Usually variable |
| Access to money | Depends on maturity dates and withdrawal terms | Generally more flexible |
| Return predictability | Greater for fixed-rate CDs | Changes when the rate changes |
| Management | Requires maturity tracking | Usually simpler |
| Emergency savings | Less suitable for money needed immediately | Often more suitable |
A savings account may be the better choice for emergency funds. A CD ladder may suit money you can leave deposited for defined periods.
Some savers use both options to balance immediate access with predictable interest earnings.
Common CD Ladder Mistakes to Avoid
Even a simple CD ladder can become less effective if you overlook important details.
Locking Up Too Much Money
Do not place every available dollar into CDs. Unexpected expenses can arise before a CD matures.
Keep accessible cash for emergencies and upcoming bills.
Ignoring Early Withdrawal Penalties
Review the withdrawal terms before opening each account. Penalties vary between institutions and CD products.
If flexibility is important, compare no-penalty CDs or other savings options, while checking whether their interest rates and restrictions fit your needs.
Focusing Only on the Highest APY
The highest advertised rate is not the only consideration.
Check whether the CD requires a large minimum deposit, has special eligibility requirements, or offers a term that fits your plans.
Forgetting Maturity Dates
Automatic renewal can be convenient, but it may result in an unwanted term or an uncompetitive rate.
Set reminders ahead of maturity and review the available choices.
Ignoring Taxes
In the United States, CD interest is generally taxable income, subject to applicable tax rules. The timing of tax reporting can depend on how interest is paid or credited and the specific account arrangements.
Consider after-tax returns when comparing savings options, and consult a qualified tax professional if your situation is complex.
Assuming All CDs Have Deposit Insurance
Verify that the financial institution is insured and that your total deposits remain within the relevant insurance limits.
Also remember that CDs issued by different institutions may have different protections depending on the issuer and product structure.
Who Should Consider a CD Ladder Strategy?
A CD ladder may be suitable for people who want a balance between predictable interest earnings and periodic access to savings.
It can be worth considering if you:
- Have money you do not need to spend immediately.
- Prefer predictable returns over stock-market volatility for this portion of your savings.
- Want to spread your maturity dates across several months or years.
- Are saving for a planned expense.
- Prefer a structured savings system.
- Can keep emergency funds outside CDs.
However, a CD ladder may be less suitable if you have high-interest debt, insufficient emergency savings, or a near-term need for all your money.
For example, paying down expensive credit card debt may be more financially beneficial than earning a modest CD yield, although your decision should also account for emergency reserves and other financial obligations.
People saving for long-term goals may also want to compare CDs with other investment options, considering their risk tolerance and time horizon.
How Much Money Do You Need for a CD Ladder?
There is no single amount required to build a CD ladder. Your starting balance depends on the minimum deposits accepted by your chosen banks or credit unions.
For example, if each CD requires a $500 minimum deposit, a three-CD ladder may require $1,500. A five-CD ladder using the same minimum would require $2,500.
These figures are examples only; minimum deposit requirements vary by institution.
If you have limited savings, you can begin with two or three CDs and add more as your savings grow.
It is usually more important to maintain an appropriate emergency fund and choose affordable deposits than to create a large ladder immediately.
Frequently Asked Questions About CD Ladder Strategy
1. Is a CD ladder strategy safe?
A CD ladder using eligible deposits at an appropriately insured U.S. bank or credit union can offer substantial protection against institutional failure within applicable insurance limits. However, it still has limitations, including early withdrawal penalties, inflation risk, and reinvestment risk.
Check the institution’s insurance status and the terms of each CD before depositing money.
2. How many CDs should I include in a ladder?
Many people use three to five CDs, but there is no required number. Your ideal structure depends on your available savings, the maturity dates you want, and the time you can leave your money deposited.
A smaller ladder can be easier to manage when you are starting out.
3. Can I withdraw money from a CD ladder at any time?
You can generally withdraw money when an individual CD matures. Withdrawing before maturity may trigger a penalty under the account agreement.
If you need frequent access to your savings, consider keeping a portion in a savings account or comparing CDs that offer more flexible withdrawal terms.
4. What happens when a CD matures?
When a CD matures, you can usually withdraw the principal and interest, transfer the funds, or renew the CD, subject to the bank’s rules.
Review the maturity notice and grace period so you can make a decision before any automatic renewal takes effect.
5. Does a CD ladder earn more interest than a savings account?
Not necessarily. A CD ladder may earn more if its CDs offer higher rates than the savings account over the relevant period. However, savings account rates can change, and the best option depends on current offers and your need for liquidity.
Compare APYs, fees, penalties, and account conditions before deciding.
6. Can beginners use a CD ladder?
Yes. A CD ladder can be relatively straightforward to manage once you understand CD terms, maturity dates, and withdrawal penalties.
Beginners can start with a small number of CDs and expand the ladder as their savings increase.
7. Should I reinvest every matured CD?
No. Reinvesting is optional. If you need the money for a planned expense or an emergency, you can withdraw it instead.
If you do not need the funds, compare current CD rates and choose a new term that matches your financial goals.
8. Is a CD ladder better than investing in stocks?
These options have different purposes. A CD ladder generally prioritizes predictable interest earnings and principal protection through eligible deposit insurance. Stocks offer greater growth potential but involve market risk and possible losses.
The appropriate choice depends on your time horizon, financial goals, and tolerance for risk.
Conclusion
A CD ladder strategy is a practical way to organize savings across Certificates of Deposit with different maturity dates. Rather than locking all your money into one long-term CD, you spread deposits across several terms and create opportunities to access portions of your savings periodically.
The strategy can provide predictable interest earnings, reduce dependence on a single reinvestment date, and help you maintain a disciplined savings routine. At the same time, it requires careful attention to early withdrawal penalties, maturity dates, inflation, and changing interest rates.
To build a suitable CD ladder, begin with a clear savings goal, maintain accessible emergency funds, compare banks and credit unions, and choose CD terms that match your financial needs. Review every account before maturity and reinvest only when doing so makes sense for your situation.
The most effective CD ladder strategy is one based on realistic savings goals, competitive interest rates, careful maturity planning, and a clear understanding of liquidity needs. When used appropriately, a CD ladder can be a useful part of a broader financial plan and help you manage savings with greater confidence.
REad Next